- FEATURED ON CEO SALES STRATEGIES PODCAST
If your CPA is “accurate,” why are you still losing hundreds of thousands in taxes every year?
Most CEOs assume their taxes are optimized because they’re filed correctly. That assumption quietly drains cash from the business year after year.
When tax is treated as compliance instead of structure, overpayments don’t show up as obvious errors. They show up as lower EBITDA, reduced reinvestment capacity, and decisions made with less capital than should be available.
The real issue isn’t what’s on the return. It’s what never should have been paid in the first place. That gap compounds annually, and by the time it’s visible, it’s already embedded in the financials and reflected in how the business is valued.
Listen to the podcast episodes also on:


Key Highlights
- Most CEOs overpay taxes because accuracy is mistaken for optimization.
- A single structural shift can unlock $700,000 in trapped cash.
- Compliance-focused CPAs quietly allow massive tax leakage to persist.
- Misclassified expenses silently compound into long-term EBITDA suppression.
- Wrong entity structure can push tax rates near 50% unnecessarily.
- Missed write-offs accumulate into six-figure losses CEOs never see.
- Tax overpayment reduces reinvestment capacity and weakens future valuation.
Most CEOs assume tax efficiency improves as the business grows.
What actually happens is inefficiency scales with revenue when structure and accuracy aren’t corrected.
From a buyer’s perspective, this isn’t optimization—it’s normalized leakage that compresses EBITDA and signals poor financial control under diligence. What looks like growth on the surface often masks capital that never stayed in the business to begin with.
By the time you notice it, it’s already embedded in every financial decision you’ve made.
About Our Guest
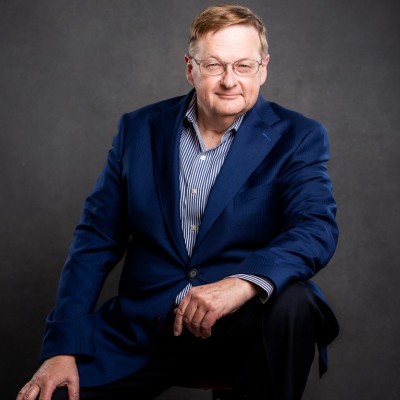
Peter Holtz
Peter Holtz has over 40 years of experience working inside the tax system, including building a firm to approximately $13 million in revenue. His work focuses on how business owners structure and report their financials—and where those decisions break down under scrutiny.
Across companies ranging from high-income W2 earners to multi-million-dollar businesses, a consistent pattern emerges: significant tax overpayment driven by inaccurate reporting, missed write-offs, and misaligned entity structures.
Summary
1. Accuracy vs Optimization Breakdown
Most businesses assume accurate tax filings mean optimized outcomes. They don’t. Accuracy only ensures compliance—it doesn’t question whether the numbers should exist in the first place. When classifications, deductions, and reporting follow default patterns, overpayment becomes normalized. It doesn’t trigger alarms because nothing is technically “wrong.” The gap only appears when someone recalculates what should have been paid under a different structure. That difference doesn’t show up gradually—it shows up all at once, usually when someone else reviews the financials with a different lens.
If your taxes haven’t been structurally challenged, assume a significant percentage is overpaid.
~ Peter Holtz
2. Structural Shifts Driving Six-Figure Impact
Entity structure isn’t a technical detail—it determines how much cash actually stays in the business. When income flows through the wrong structure, tax rates escalate without resistance. The impact isn’t marginal. It compounds at scale, especially past $5M in revenue. What appears as a normal tax burden is often a structural inefficiency embedded in how the business is set up. The shift isn’t visible in year-to-year comparisons. It becomes visible when the same income is run through a different structure and the retained cash changes materially.
If tax is only reviewed after the fact, the outcome was already locked in.
~ Doug C. Brown
3. Compliance-Only CPA Exposure
Most CPAs operate as compliance processors, not strategic advisors. Their role is to file based on what already happened, not challenge what should have happened. That creates a blind spot. If no one is actively questioning structure, classification, and timing, then inefficiencies persist by default. The business doesn’t feel the loss directly—it just operates with less capital than it should. Over time, that missing capital translates into slower growth, constrained hiring, and decisions made under tighter financial conditions than necessary.
Most tax filings aren’t optimized—they’re just processed, whether the numbers make sense or not.
~ Peter Holtz
4. Misclassification Compounding Effect
Small classification errors rarely look significant in isolation. A miscategorized expense, an overlooked asset, or an incorrect line item doesn’t immediately raise concern. But those errors don’t reset each year—they stack. Over time, they distort the financial picture and reduce the ability to capture legitimate deductions. The result isn’t a single large mistake, but a pattern of under-optimization that compounds silently. By the time it’s identified, the accumulated impact has already affected multiple years of cash flow and financial positioning.
5. Entity Structure and Tax Rate Escalation
Pushing business income through the wrong entity structure can quietly push total tax exposure toward 50% when federal and state are combined. This doesn’t require aggressive assumptions—it happens through default setups that were never revisited as the business scaled. What begins as a simple structure at lower revenue levels becomes inefficient as income grows. The issue isn’t visibility—it’s inertia. Without reevaluation, the structure remains in place while the financial impact increases year after year.
6. Missed Write-Off Accumulation
Write-offs aren’t usually missed in obvious ways. They’re missed because no one is actively looking for them. Assets go unrecorded. Legitimate business usage goes unclaimed. Entire categories of deductions are ignored because they weren’t captured correctly at the start. Individually, each missed opportunity feels minor. Collectively, they represent a significant reduction in retained earnings. The business continues operating as if those costs are unavoidable, when in reality they were never properly accounted for.
7. Tax Impact on Valuation and Reinvestment
Tax overpayment doesn’t just affect cash—it affects how the business is perceived. Lower retained earnings reduce reinvestment capacity, which limits growth options over time. From a buyer’s perspective, excess tax payments signal inefficiency in financial management. That inefficiency gets priced into the deal. What could have been reinvested into revenue, margin, or expansion instead exits the business permanently. The result is a business that appears less optimized, both operationally and financially, than it actually could be.
You’re not short on capital—you’ve already paid it out through tax inefficiency.
~Doug C. Brown
Reflection & Call to Action
At a certain point, it’s no longer about whether taxes are filed correctly. The real question is whether the structure behind those filings is costing more than it should—and whether that gap has already compounded.
- If your tax filings are “accurate,” what makes you certain they’re economically optimized?
- How much capital has already left the business simply because no one challenged the structure?
- If a buyer recalculated your taxes today, what would they find that you didn’t?
If this feels uncomfortably familiar, a brief conversation usually clarifies whether the issue sits in the numbers, the structure, or the assumptions behind them.
If that’s the clarity you want, email youmatter@ceosalesstrategies.com.
Related Content & Resources
Connect with Doug C. Brown
Diagnostic:
Guest Resources – Peter Holtz
Ready to Build Compounding Growth?
Want to explore how what happens after the sale shapes your business growth and long-term value?